How to choose a payment gateway depends on more than the headline transaction fee: you need to compare the full cost, settlement flow, integrations, security and support. Use this 12-point checklist to compare a conventional gateway with direct UPI plus payment verification for your Indian business.
Start with your payment mix: how much is UPI?
First separate the question “Which payment methods do my customers use?” from “Which provider has the longest feature list?” If UPI is the main method for your orders, invoices or renewals, a traditional gateway may add a layer of per-transaction pricing and later settlement that you do not need for every payment.
RBI’s Guidelines on Regulation of Payment Aggregators and Payment Gateways describe payment aggregators as entities that receive, pool and transfer customer payments to merchants, while payment gateways provide technology to route and facilitate transactions without handling funds. That distinction should be part of your shortlist from the start.
Make a simple payment-mix table for the last 30 days:
| Payment type | Number of payments | Total value | Must be automated? |
|---|---|---|---|
| UPI | ₹ | Yes / No | |
| Cards | ₹ | Yes / No | |
| Net banking or wallets | ₹ | Yes / No | |
| Cash or bank transfer | ₹ | Yes / No |
If most of your online payments are UPI and you already have a business UPI account, compare a gateway with a verification service on the same sheet. PaymentSetu lets the customer pay your own Paytm Business or PhonePe Business merchant account; it matches the UTR and amount to the order and sends a webhook. It does not hold the payment.
For a broader starting point, see our guide to accepting UPI payments for a small business.
What you need before comparing providers
Collect these figures and requirements before opening pricing pages:
- Average and largest order value.
- Monthly payment count and monthly payment value.
- UPI percentage, plus the card and other methods you must accept.
- Your current platform: WooCommerce, WHMCS, a custom website, app or manual invoices.
- The bank or merchant account where you want money to land.
- Your required settlement timing and reconciliation process.
- The person who will handle failed payments, refunds, disputes and technical support.
Keep the provider’s pricing page, merchant agreement, integration documentation and support terms together. A low advertised fee is not comparable until you know whether GST on the fee, platform charges, refunds, chargebacks, reserves or minimum commitments are added.
Step 1: Calculate the true per-payment cost
Why this matters: a small percentage becomes a large monthly expense at scale, while a flat plan may be easier to budget.
Write down this calculation for every option:
Monthly payment cost = transaction fees + GST on those fees
                       + platform or subscription fees
                       + refund, chargeback or other stated charges
For example, if a provider charges a hypothetical 2% transaction fee on ₹5,00,000 of monthly sales, the fee before any applicable tax is ₹10,000. Do not compare that with a subscription price until you have checked the tax and every fixed charge.
Success looks like a monthly rupee figure for each option, not just a percentage copied from a homepage. Our payment gateway fees guide shows the same calculation method across different sales levels.
Step 2: Check where the money goes and when
Why this matters: cash flow and control can matter more than a small difference in the quoted fee.
Ask these exact questions:
- Does the customer’s payment go straight to my own merchant account, or is it collected and transferred later?
- What is the stated settlement cycle for each payment method?
- Can weekends, holidays, refunds, disputes or risk reviews change the timing?
- Are reserves, rolling holds or minimum balances possible under the agreement?
- Which party handles the customer’s payment complaint?
Success looks like a written answer that you can map to your cash-flow needs. With PaymentSetu’s direct-UPI model, the customer pays your connected merchant account and the service verifies the payment; there is no PaymentSetu wallet or pooled balance.
Step 3: Confirm the payment methods you actually need
Why this matters: accepting every possible method can add complexity that your customers never use.
Mark each method as required, useful or unnecessary: UPI QR, UPI intent, cards, net banking, wallets, international cards, recurring payments, payment links and bank transfers.
Do not choose based on a logo wall. Check whether the method works on your checkout, whether the amount and order reference are passed correctly, and how you will identify a completed payment in your records.
Success looks like a short list of required methods with a tested customer journey for each one. If UPI covers your main use case, a focused UPI setup can be simpler than paying for unused methods.
Step 4: Match the integration to your platform
Why this matters: the best commercial terms are not useful if your team cannot install, configure and maintain the integration.
Check for a supported plugin or module before planning custom development. For WooCommerce, confirm where the payment method appears, how the order changes to paid, and what happens when the customer returns without completing payment. For WHMCS, check invoice status, callback handling and the module’s configuration fields.
PaymentSetu provides a WooCommerce plugin and a WHMCS gateway module. A custom build can use the API, but owners should first ask whether a maintained platform integration already covers the workflow.
Success looks like a documented test installation on a staging site, with one successful payment and one cancelled or incomplete payment recorded correctly.
Step 5: Inspect the API, webhook and status model
Why this matters: payment automation fails when the order system cannot reliably learn the final status.
Look for:
- A create-payment or create-order endpoint.
- A server-side status lookup for reconciliation.
- Signed webhooks, with clear signature verification instructions.
- A unique order or transaction ID that you control.
- Retry behaviour and a documented response to duplicate notifications.
- A way to distinguish success, pending, failed, expired and refunded states.
Never mark an order paid from a browser redirect or a customer-uploaded screenshot alone. Verify the server-side event, validate the amount and order ID, and make the handler idempotent so the same notification cannot fulfil an order twice.
Success looks like your developer can draw the complete order flow before writing code: create order, show payment instructions, receive notification, verify the signature, check amount and update the order once.
Step 6: Compare reconciliation and reporting
Why this matters: payment acceptance is only half the work; you also need to match money to orders, invoices and bank entries.
Ask whether the dashboard shows order ID, amount, timestamp, payment reference or UTR, status and settlement or account details. Check whether you can filter by date and export the records your accountant needs. For recurring billing or hosting renewals, confirm that the invoice number remains visible through the payment lifecycle.
Success looks like a sample export that lets you answer three questions quickly: which order was paid, which UPI credit belongs to it, and which payments still need review.
Step 7: Review refunds, disputes and failed payments
Why this matters: your support team needs a clear answer when a customer says money was debited but an order is still pending.
Before signing up, document what happens for a failed, pending, reversed, duplicate or wrongly paid transaction. Ask who communicates with the customer, whether your team can add an internal note, and how you will reconcile a payment that arrives without a matching order.
For direct UPI, your team should keep a clear policy for checking the payment reference and deciding how to handle an unmatched credit. The verification layer should help identify the payment; it should not be described as a replacement for your customer-service or refund process.
Success looks like a one-page internal playbook with an owner, the evidence to collect and the next action for every status.
Step 8: Check merchant onboarding and account ownership
Why this matters: the payment account should belong to the business that earns the money, and onboarding requirements should be understood before launch.
Confirm whose merchant account is used, whose name appears to the customer, what business documents the provider requests, and whether your team can access the account independently. Do not treat a technology service as the owner of your payment account.
For a UPI-first model, verify that your business has an active merchant account with the supported provider you intend to connect. PaymentSetu currently connects Paytm Business and PhonePe Business accounts. The customer pays that account directly.
Success looks like a confirmed account owner, a documented login and access process, and no ambiguity about where the funds land.
Step 9: Check security controls you can operate
Why this matters: security is not just a provider feature; your checkout and backend must use it correctly.
At minimum, check that the provider documents HTTPS requirements, API-key handling, webhook signature verification, access roles and logs. Ask how credentials are rotated and whether test credentials are available. Keep secret keys on your server, never in browser JavaScript or a public repository.
For signed webhooks, verify the signature over the exact raw request body before parsing it, reject invalid timestamps if the provider supplies one, and store an event ID to prevent replay. Limit the webhook endpoint to the events and actions it needs.
Success looks like a small security checklist that your developer can demonstrate in a test environment, including an invalid-signature test.
Step 10: Verify checkout and customer experience
Why this matters: a technically correct payment flow can still lose orders if the customer is unsure what to do next.
Test on Android, iPhone and desktop. Check the amount, merchant name, order reference, QR or intent hand-off, success message and return path. Make the pending state clear; do not tell a customer that an order is paid until your server confirms it.
For QR-based payments, check that the QR contains the intended UPI ID and amount, that it cannot be silently replaced in your page template, and that the customer has another way to get help. Use a fixed amount for an order where your workflow needs exact matching.
Success looks like a new customer can complete the payment without instructions from your support team, while your staff can still locate the order from the payment reference.
Step 11: Compare support, documentation and ownership
Why this matters: the person who answers a billing question may not be the person who can fix a webhook or plugin issue.
Record the support channel, published hours, response expectations, escalation route and documentation quality. Ask whether support covers configuration only or also helps diagnose API responses, callbacks and order-status mismatches.
Also check who owns the integration code. A plugin that can be updated without rewriting your checkout is easier to maintain than a one-off script known only to a former contractor.
Success looks like a support test: send one technical question before you subscribe and save the answer with your implementation notes.
Step 12: Read the commercial and exit terms
Why this matters: the agreement defines what happens when your volume, business model or payment mix changes.
Check billing frequency, taxes, renewal, unused credits, cancellation, data access, export format, refund terms, downtime communication and any volume or risk conditions. Make sure the plan you compare is available to your business category and country.
For PaymentSetu, the published plans are billed per 30 days: Starter is ₹399 for 100 credits, Pro is ₹999 for 1,000 credits, and Business is ₹1,499 for 100,000 credits. One credit equals one successful payment verified. Review the current plan options against your expected verified-payment count rather than comparing only the sticker price.
Success looks like a saved copy of the terms and a plan for exporting your records if you ever change your payment setup.
Score three options on the checklist
Use a simple 0–2 score for each criterion: 0 means missing or unsuitable, 1 means workable with a manual process, and 2 means it meets your requirement with clear documentation. Give the criteria that affect cash flow and order accuracy a higher weight.
| Criterion | Weight | Gateway A | Gateway B | Direct UPI + verification |
|---|---|---|---|---|
| Total monthly cost at your volume | 3 | |||
| Required payment methods | 2 | |||
| Money reaches the intended account | 3 | |||
| Settlement and cash-flow fit | 3 | |||
| Platform integration | 2 | |||
| Webhooks and status lookup | 3 | |||
| Reconciliation and export | 2 | |||
| Security controls | 3 | |||
| Support and documentation | 2 |
Multiply each score by its weight, then write down the one assumption behind every score. This prevents a provider from winning because of a single low headline fee while failing your settlement or integration requirements.
When direct UPI plus verification wins
Direct UPI plus verification is worth comparing seriously when your customers already prefer UPI, you have your own merchant account, and you want orders or invoices to update automatically. It can be a strong fit for a WooCommerce store, WHMCS hosting business, SaaS or service provider, freelancer, clinic or retail counter that needs matching and notifications rather than a broad set of payment instruments.
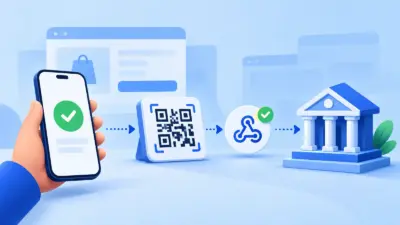
The flow is straightforward:
- Your system creates an order or invoice.
- The customer pays your own merchant UPI account through the generated QR or payment instructions.
- PaymentSetu matches the amount and UTR to the order.
- Your plugin, API integration or webhook receives the verified status.
- Your system fulfils the order or marks the invoice paid.
This model is different from a payment gateway and should be evaluated as such. It does not aim to replace every payment method; it gives a UPI-heavy business a direct-account workflow with a flat plan and 0% commission on payments. The Pro plan is designed for growing WooCommerce, WHMCS and service businesses verifying up to 1,000 UPI payments in a 30-day period.
Verify your shortlist before launch
Do not make the final decision from a demo video. Run a small controlled test and record:
- The exact customer amount and order ID.
- The payment account that receives the money.
- The status shown to the customer and to your server.
- The notification, signature and duplicate-event behaviour.
- The dashboard record and export row.
- The support response to one setup question.
Repeat the test on your actual platform. A WooCommerce checkout and a WHMCS invoice can have different status and callback requirements even when they use the same payment method.
Troubleshooting common selection mistakes
Choosing the lowest percentage: Recalculate the monthly rupee cost after GST and fixed charges. A low rate is not a low cost at every volume.
Treating a redirect as proof of payment: A browser can close, be refreshed or be manipulated. Use a server-side status check or signed webhook and compare the amount and order ID.
Ignoring the settlement account: Ask whether funds are paid to your own merchant account or transferred after collection. The answer changes cash-flow planning and reconciliation.
Buying features you will not use: Start with your payment mix. If UPI is dominant, compare a focused direct-UPI workflow instead of paying for methods you do not require.
Skipping the exit test: Export a sample report and confirm you can retrieve your records before you commit. This is especially important for recurring invoices and high-volume orders.
Questions to ask before signing up
Send these questions to every shortlisted provider and keep the answers:
- What is the complete monthly cost for my expected volume, including GST and fixed charges?
- Where does the customer’s money go, and what is the settlement timeline?
- Which plugins, modules, APIs and webhook events are supported today?
- How are pending, duplicate, failed, reversed and refunded payments represented?
- Can I export order IDs, payment references, amounts and statuses?
- What security steps must my developer implement?
- Who owns the merchant account, data and integration credentials?
- Which support channel handles payment and technical questions?
The provider that gives the clearest answers to these questions is easier to operate than the one with the most impressive feature list.
FAQ
What is the most important factor when choosing a payment gateway?
Start with total cost and cash flow, then check whether the integration reliably marks orders paid. The right choice must fit your payment mix, platform, reconciliation process and support capacity.
Should a small business choose a payment gateway or direct UPI?
Choose a gateway when you genuinely need several payment methods and its settlement model works for you. Compare direct UPI plus verification when most customers pay by UPI and you want payments to go into your own merchant account with automated order matching.
How do I compare payment gateway fees in India?
Calculate the fee on your real monthly value, add GST and fixed charges, and include refund, dispute or reserve terms where applicable. Compare that monthly result with any flat plan, then check what payment methods and integrations are included.
What should I check in a payment gateway API?
Look for server-side status lookup, signed webhooks, unique transaction IDs, clear payment states, retries and duplicate-event handling. Test signature verification and idempotency before accepting live orders.
Is PaymentSetu a payment gateway?
No. PaymentSetu is a payment verification service: the customer pays the merchant’s own connected Paytm Business or PhonePe Business account, and PaymentSetu matches the payment and sends the verified status to the merchant’s system.